Shortcut Trick
Ratio of Profit to Loss is 5 : 1.
Difference in Selling Prices = 4550 − 3290 = 1260.
Divide difference by sum of ratio parts (5 + 1 = 6): 1 unit = 1260 ÷ 6 = 210.
Cost Price (CP) = Loss SP + 1 unit = 3290 + 210 = 3500.
New Selling Price (SP) for 20% profit = 3500 × 120 ÷ 100 = 4200.
∴ The correct answer is Rs. 4200.

Alternate Method
Given: SP1 = Rs. 4550, SP2 = Rs. 3290, Profit = 5 × Loss, Target Profit = 20%.
Formulas: Profit = SP − CP | Loss = CP − SP | New SP = CP × (100 + P%) ÷ 100
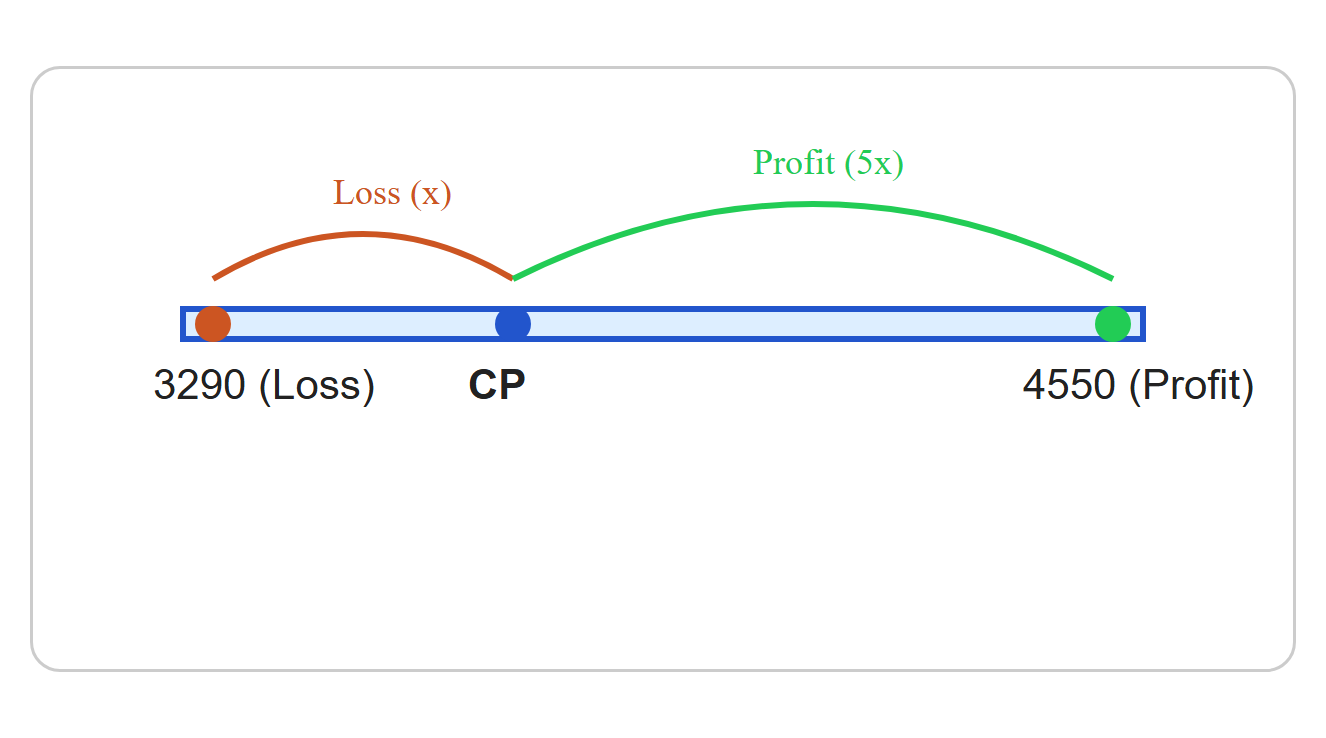
⇒ Let the loss be x. Then Profit = 5x.
⇒ (4550 − CP) = 5 × (CP − 3290)
⇒ 4550 − CP = 5CP − 16450
⇒ 6CP = 21000 ⇒ CP = 3500
⇒ New SP = 3500 × (120 ÷ 100) = 4200.
∴ The correct answer is Rs. 4200.
Additional Information
Cost Price Calculation
When Profit and Loss are related for the same article at different prices, the CP acts as the central reference point. CP = (n × SPloss + SPprofit) ÷ (n + 1) where Profit = n × Loss.
Profit Percentage
Profit % is always calculated on the Cost Price (CP) unless stated otherwise. Formula: Profit% = (Profit ÷ CP) × 100.